How to protect assets from Medicaid? Many people assume they have to spend everything down before Medicaid pays for care. That’s not accurate, and it can leave nothing behind for a spouse or family. Several legal strategies exist, each suited to a different timeline and situation.
This guide covers all six, plus a table to match the right one to your circumstances.
1. What Does It Mean to Protect Assets From Medicaid?
Protecting assets from Medicaid means legally lowering your countable assets below your state’s limit, usually $2,000 for a single senior, without losing full control of your money.
This matters because Medicaid only pays for long-term care once your countable assets are that low, and spending everything directly can leave nothing for a spouse or family.
“Protecting” assets is a legal planning process, different from hiding assets, which violates the look-back rule and can trigger penalties.
This mainly applies to long-term care Medicaid for seniors and people with disabilities, not regular MAGI Medicaid used by younger adults.
2. What Are the Core Strategies to Protect Assets From Medicaid?
Six strategies come up most often in Medicaid planning, each suited to a different situation. Some work best years in advance, while others apply even close to needing care. The sections below cover each one.
Medicaid Asset Protection Trusts
This strategy involves moving assets into an irrevocable trust at least 5 years before applying.
A Medicaid Asset Protection Trust is the most common tool for this, with its own rules on trustees and cost.
Spousal Protection Strategies
When one spouse needs care, and the other doesn’t, assets can be shifted to the healthy spouse up to the Community Spouse Resource Allowance limit, without triggering a penalty.
Medicaid-Compliant Annuities
A lump sum of cash converts into a fixed income stream through an annuity that meets specific Medicaid rules, moving the money out of countable assets and into income instead.
Spending Down Assets on Allowed Expenses
Excess cash can go toward allowed expenses, such as paying off a mortgage, home repairs, or a prepaid funeral plan, rather than being given away.
Protected and Exempt Assets
Certain assets, like a primary home (subject to state equity limits if single, or completely exempt if a spouse resides there), one vehicle, and personal belongings, are already excluded from Medicaid’s asset count in most cases.
Special Needs Planning
For a family member with a disability, a special needs trust can hold assets on their behalf without affecting their own Medicaid eligibility.
>>> Read more: How To Find An Emergency Dentist That Accepts Medicaid For Adults?
3. How Does the Look-Back Period Affect Asset Protection?
Medicaid checks the 60 months before you apply for gifts or asset transfers below fair market value. Strategies like an MAPT or gifting money to family trigger this rule and cause a penalty period if done too close to applying.
Spousal transfers, annuities, and paying off debt generally do not trigger it, since nothing is given away below value.
Medicaid penalty period length depends on the amount transferred divided by the average monthly care cost in the state, not a fixed number of months.
4. Which Strategy Fits Your Situation?
The right strategy depends on your timeline and who else the assets need to protect. Someone with years to plan has different options than someone who needs to qualify soon. This table lays out common situations side by side.
| Your Situation | Strategy Worth Considering |
| Healthy now, no care needed for 5+ years | Medicaid Asset Protection Trust |
| One spouse needs care, other stays home | Spousal transfer up to the CSRA limit |
| Need to qualify soon, have a lump sum | Medicaid-compliant annuity |
| Excess cash sitting in savings | Pay off debt or convert to an exempt asset |
| A family member already provides care | Personal care agreement |
5. What Medicaid Planning Mistakes Should You Avoid?
A few recurring mistakes show up across Medicaid planning cases, and most of them come down to timing or paperwork rather than the strategy itself.
- Improper gifts: giving away money or property below fair market value within the look-back window is one of the most common triggers for a penalty period
- Late planning: starting a trust or other strategy only after care is already needed limits which options are still available
- Wrong trust type: using a revocable trust instead of an irrevocable one does not protect assets, since Medicaid still counts revocable trust assets as belonging to the applicant
- Missing documentation: incomplete records of transfers or trust funding can slow down an application or trigger unnecessary questions during review
6. Managing Medicaid Planning Also Requires Staying Connected
Protecting your assets is a major milestone, but managing your care also means keeping lines of communication open. The good news? High phone bills don’t have to be part of the equation. Here is why staying connected might cost you less than you think.
If you’re already enrolled in Medicaid, you likely qualify for Lifeline, a federal program that knocks up to $9.25 off your monthly phone service or internet service bill (up to $34.25 on Tribal lands). It’s a bill discount, not a free-device gimmick, though paired with the right provider it can come with one.
Qualifying works through any of the following, not just Medicaid:
- SNAP
- SSI
- Section 8
- Veterans Pension, etc.
- Or with your household income at or below 135% of the federal poverty guidelines
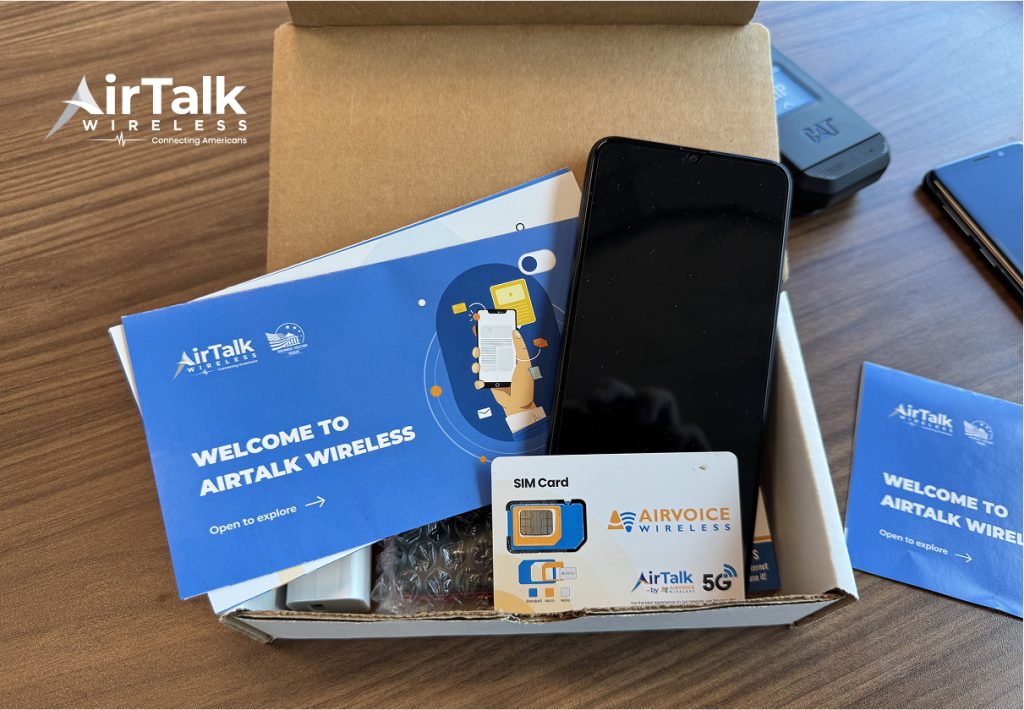
For your information, you do not apply directly to the government for the benefit. Instead, you will apply to Eligible Telecommunications Carriers (ETCs). These carriers will be in charge of the enrollment process and, in many cases, offer a promotional device along with the benefit.
Cintex Wireless is one of those carriers. The carrier layers its own device promotions on top of the Lifeline discount, so an eligible applicant can end up with a free phone and a $0 monthly bill rather than just a smaller one.
Now, it has merged into AirTalk Wireless, another ETC have years of experience in the industry. This means new applicants now have access to a broader phone selection and quicker application.
>>> Read more: Free Phone Medicaid Program: Claim $0 Phones and Monthly Service
7. Frequently Asked Questions
Q1. What are the disadvantages of a Medicaid asset protection trust?
Direct control of the assets is given up once they go into the trust, since it cannot be changed or canceled. Setup typically costs $2,000 to $12,000, and the trust only protects assets fully after the 5-year look-back period passes.
Q2. How much money can I have in savings and still get Medicaid?
It depends on how you qualify. Adults aged 19 to 64 who qualify through Medicaid expansion generally face no asset limit at all. Seniors, people with disabilities, or anyone applying for long-term care Medicaid usually face a $2,000 limit for a single applicant in 2026.
Q3. Does putting money in a trust protect it from Medicaid?
Only if the trust is irrevocable and set up correctly at least 5 years before applying. A revocable trust does not protect assets, since Medicaid still counts them as belonging to the person who created it.
Conclusion
How to protect assets from Medicaid? It comes down to timing more than picking the perfect strategy. Acting early keeps more options open than waiting until care is already needed.
Speaking with an elder law attorney before transferring any assets is a common next step people take to confirm which strategy fits their specific situation.