Medicaid trust NY rules trip up a lot of people who read the standard 5-year look-back rule and assume it applies everywhere the same way. New York actually has its own set of rules for home care that work differently from nursing home Medicaid.
This guide separates the two situations and covers the pooled income trust, an option fewer people know about.
1. What Is a Medicaid Trust NY?
A Medicaid trust in New York, most often a Medicaid Asset Protection Trust (MAPT), is an irrevocable legal arrangement that moves assets out of a person’s name so Medicaid does not count them toward the state’s Medicaid asset limit.
It lets someone qualify for long-term care Medicaid while keeping their home and savings within the family.
Some people also call this a Medicaid Planning Trust or Home Protection Trust. It works differently than a revocable living trust, which New York still counts as a countable asset since the person retains control.
A MAPT can apply to both nursing home and home care planning, though the specific rules differ between the two.
2. How Does a Medicaid Asset Protection Trust Work in NY?
Setting up a MAPT starts with transferring ownership of assets, such as a home or savings, into the trust. A third party, often an adult child, is named as trustee and manages the trust going forward.
The person who created the trust gives up direct ownership and cannot cancel it, though they can typically keep the right to live in the home and collect income the trust generates.
New York enforces a strict rule here: the trustee cannot be the person who created the trust, or their spouse.
Income generated by trust assets that is paid directly to the creator counts toward Medicaid’s monthly income limit. If an individual has excess monthly income, New York allows them to use a Pooled Income Trust (rather than a MAPT) to protect that surplus income while maintaining Medicaid eligibility.
3. What NY Medicaid Trust Rules Should You Understand?
New York treats nursing home Medicaid and home care Medicaid differently when it comes to trusts.
The two categories follow separate timelines and separate enforcement, which is where a lot of confusion starts. This table lays out the main differences.
| Rule | Nursing Home Medicaid | Home and Community Based Care |
| Look-back period | 60 months (5 years) | Currently none in NY, a 30-month look-back is planned but not yet in effect |
| Penalty for recent transfers | Yes, if assets moved within 60 months | Not currently enforced |
| Trustee requirement | Third party, not the grantor or spouse | Same |
| Estate recovery after death | Trust assets protected once look-back clears | Trust assets protected once look-back clears |
Assets That May Receive Special Treatment
A few assets outside the trust itself may already be excluded from Medicaid’s asset count, depending on the situation:
- A primary home, if the equity interest is within the state limit and the owner intends to return
- One vehicle
- Personal belongings and household items
- Prepaid burial and funeral arrangements
- Term life insurance with no cash value
>>> Read more: Medicaid Planning: An Ultimate Guide To Long-Term Healthcare
4. What Is a Pooled Income Trust in NY, and How Is It Different?
A pooled income trust (established under Social Security Law § 366 1-a) is a special New York tool for individuals whose monthly income exceeds Medicaid limits.
Run by a non-profit organization, the trust allows you to deposit your surplus income each month into a dedicated sub-account. The non-profit trustee then uses those funds directly to pay your living expenses, such as rent, property taxes, or utility bills, allowing you to stay within Medicaid’s income threshold for home care.
Depositing excess income each month lowers a person’s countable income to meet Medicaid’s limit.
This option is open to disabled individuals of any age, unlike a MAPT, which is mainly used by seniors planning ahead of time. It must be established and run by a nonprofit association and cannot be self-managed.
A common scenario involves someone who needs home care now but has monthly income slightly above the eligibility limit.
5. How Much Does a Medicaid Trust Cost in NY?
Setting up a Medicaid Asset Protection Trust in New York typically costs between $2,000 and $12,000.
The price depends on the complexity of the person’s assets, whether the arrangement is bundled with a will or power of attorney, and whether a faster crisis plan is needed because care is required soon.
6. Managing Medicaid Planning Also Means Staying Connected
While establishing a trust protects your assets, enrolling in Medicaid also automatically qualifies you for other federally supported assistance programs, including monthly telecommunication savings through Lifeline.
Lifeline helps you lower the monthly phone service or internet service through a monthly discount, up to $9.25 a month standard or $34.25 a month on Tribal lands.
Medicaid enrollment already qualifies a household. SNAP, SSI, Section 8, and Veterans Pension also qualify, as does income at or below 135% of the federal poverty guidelines.
Importantly, after confirming you are qualified for Lifeline, households need to apply to Eligible Telecommunications Carriers (ETCs) to get that support.
Cintex Wireless is one of the aforementioned ETCs that combine this discount with its own device promotions, which is how eligible applicants can receive a free Lifeline service plan, including:
- Free or discounted smartphone from well-known brands
- Unlimited talk, text, and a monthly data allowance (varies by state)
- Other telecommunication benefits
UPDATE: Cintex Wireless has merged into AirTalk Wireless. The merger brings a larger device selection and a more satisfying enrollment process for eligible customers on either side of the transition.
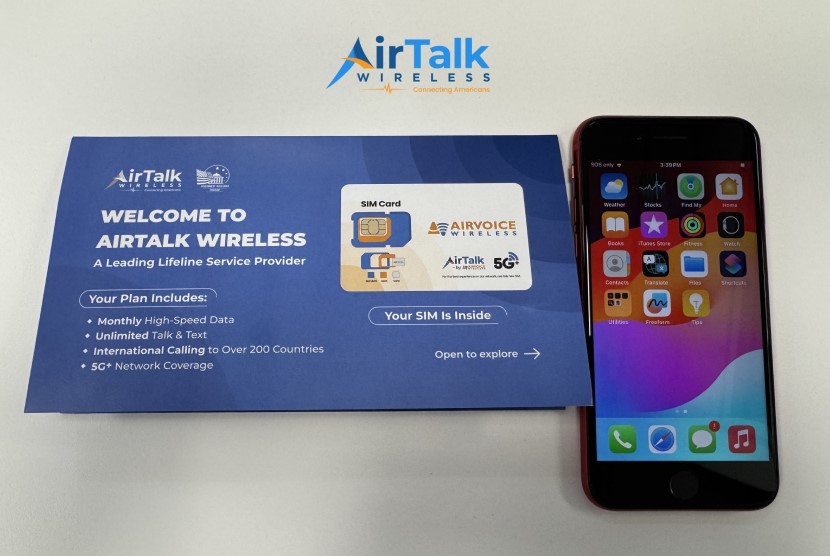
IMPORTANT: The government does not subsidize devices. Lifeline programs cover basic service costs only. Free or discounted devices, upgrade plans, or top-ups are exclusive benefits provided by AirTalk Wireless and Cintex Wireless as part of the promotional offers. Terms and conditions apply. Limited-time promotion—offers vary by state, stock availability, and eligibility.
>>> Read more: Free Government Phone in NY: How to Claim $0 Phone with Free Services
7. Frequently Asked Questions
Q1. What is the downside of a Medicaid trust NY?
Control of the transferred assets passes permanently to the trust once it’s set up, and the arrangement cannot be canceled. It also takes time to take full effect, since New York’s look-back period has to clear before the assets are fully protected.
Q2. Does putting your home in a trust protect it from Medicaid in NY?
In cases where the trust is irrevocable and structured correctly, yes. A revocable trust does not offer this protection, since New York still counts those assets as belonging to the person who created it.
Q3. How much money can you have in the bank and still get Medicaid in NY?
For 2026, the Medicaid asset limit for seniors and individuals with disabilities in New York is $31,175 for an individual (and $42,312 for a married couple). An irrevocable Medicaid trust allows individuals with assets above these limits to protect their home and savings while qualifying for long-term care benefits.
Conclusion
Medicaid trust NY planning comes down to one core distinction: New York currently has no look-back period for home care, though that could change once the 30-month rule takes effect.
Speaking with an elder law attorney in New York before moving any assets into a trust is a common next step people take. That conversation can clarify which rules apply to a specific situation before any paperwork gets filed.